
£50,000 After Tax
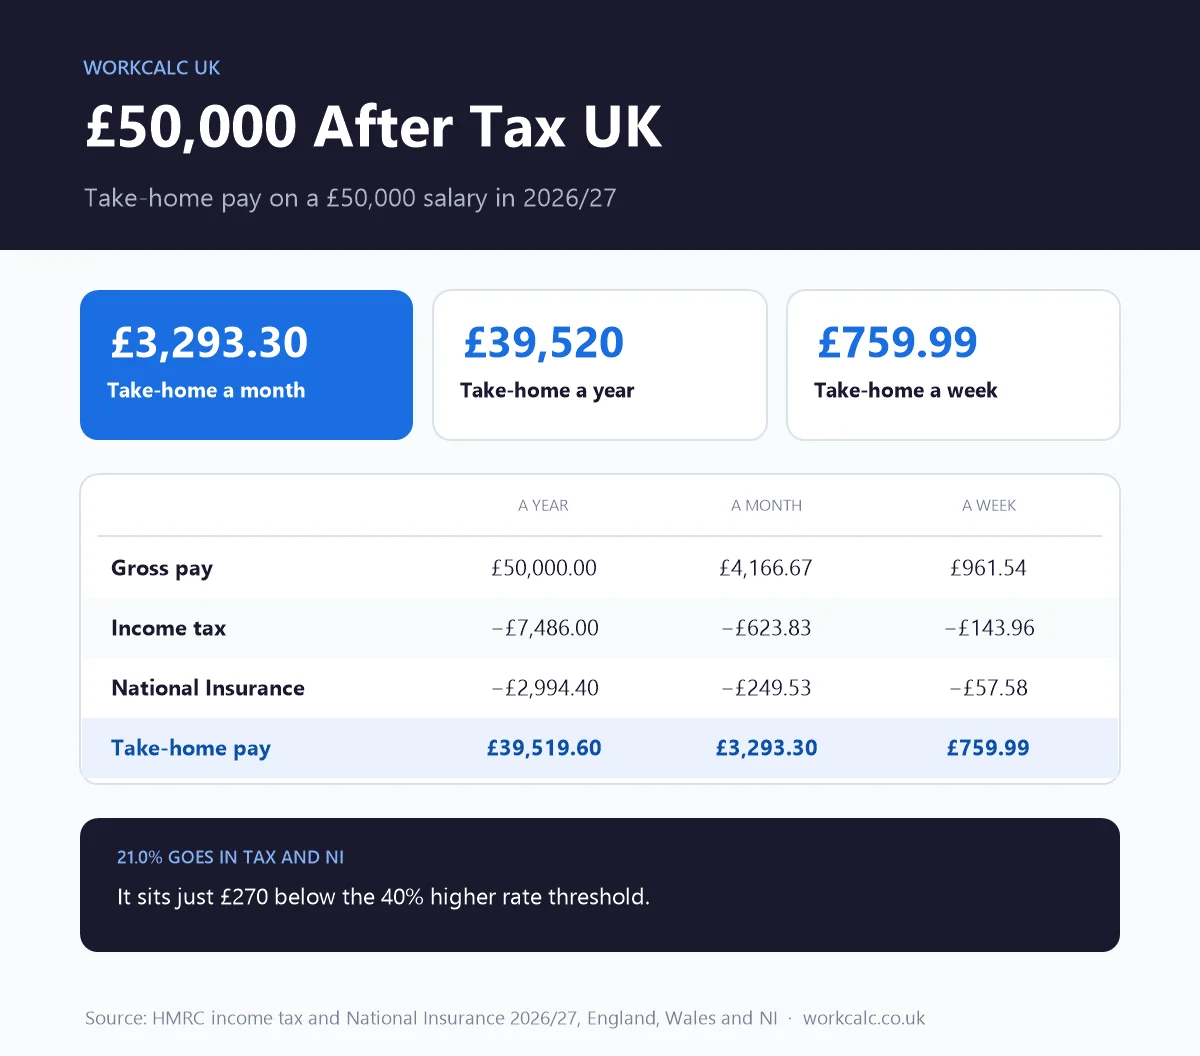
A £50,000 salary leaves £39,520 a year after income tax and National Insurance, which is £3,293 a month or £760 a week in 2026/27. It sits just £270 below the 40% higher rate threshold.
Adjust for your situation
£50,000 after tax: the short answer
A salary of £50,000 leaves £39,519.60 after income tax and National Insurance in 2026/27. Paid monthly that is £3,293.30, and 21.0% of the salary goes on the two deductions.
| Year | Month | Week | |
|---|---|---|---|
| Gross pay | £50,000.00 | £4,166.67 | £961.54 |
| Income tax | −£7,486.00 | −£623.83 | −£143.96 |
| National Insurance | −£2,994.40 | −£249.53 | −£57.58 |
| Take-home pay | £39,519.60 | £3,293.30 | £759.99 |
How the tax on £50,000 is worked out
- Personal allowance: the first £12,570 is tax-free
- Basic rate: 20% on £37,430 = £7,486.00
- National Insurance: 8% on £37,430 = £2,994.40
Your effective rate is 21.0%, but the rate on the next pound you earn is 28%. That second figure is the one to use when you weigh up overtime, a bonus or a pay rise.
£50,000 is £270 below the higher rate
The higher rate threshold is £50,270, so on £50,000 all of your income is still taxed at the basic rate. Your next £270 is taxed at 20% with 8% National Insurance. After that, tax on each pound rises to 40% while National Insurance falls to 2%, a combined 42%.
A £1,000 pay rise straddles both rates and adds £617.80 to take-home pay. A £5,000 rise adds £2,938, so you keep 59% of it.
Two allowances that change at £50,270
Marriage Allowance. If your spouse or civil partner earns under £12,570, they can transfer £1,260 of their personal allowance to you, saving up to £252 a year. You lose eligibility once you become a higher rate taxpayer.
Personal Savings Allowance. Basic rate taxpayers can earn £1,000 of savings interest tax-free, but higher rate taxpayers get £500. A rise over £50,270 halves the allowance.
Staying below the line
If a rise would take you over £50,270, increasing pension contributions by the same amount keeps your taxable income in the basic rate band and protects both allowances.
£50,000 a year as an hourly rate
| Contracted week | Before tax, per hour | After tax, per hour |
|---|---|---|
| 35 hours | £27.47 | £21.71 |
| 37.5 hours | £25.64 | £20.27 |
| 40 hours | £24.04 | £19.00 |
£50,000 is £25.64 an hour on a 37.5-hour week, almost exactly double the National Living Wage. Over 260 working days a year, £50,000 is £192.31 a day before tax and £152.00 after.
Overtime and bonuses on £50,000
With only £270 of basic rate band left, nearly all extra pay on £50,000 is taxed at 42%. That changes what overtime is worth part of the way through the year:
| Bonus or overtime | Extra take-home | You keep |
|---|---|---|
| £1,000 | £617.80 | 62% |
| £2,000 | £1,197.80 | 60% |
| £5,000 | £2,937.80 | 59% |
| £10,000 | £5,837.80 | 58% |
At your plain rate of £25.64 an hour, the first ten and a half hours of overtime in the tax year are worth £18.46 each after deductions. Once those have used up the £270, every further hour is worth £14.87. At time and a half the later hours are worth £22.31. The Overtime Calculator shows the effect on a single payslip.
£50,000 after tax with a student loan
| Plan | Repays above | A year | Take-home |
|---|---|---|---|
| Plan 1 | £26,900 | £2,079.00 | £37,441 |
| Plan 2 | £29,385 | £1,855.35 | £37,664 |
| Plan 4 (Scotland) | £33,795 | £1,458.45 | £38,061 |
| Plan 5 | £25,000 | £2,250.00 | £37,270 |
| Postgraduate Loan | £21,000 | £1,740.00 | £37,780 |
Every plan is in repayment at this salary. Each takes 9% of income above its own threshold, or 6% for a Postgraduate Loan, so two loans stack rather than replace each other.
Pension contributions on £50,000
A 5% contribution puts £2,500 a year into your pension. Through a net pay scheme it reduces take-home pay by £2,000, because the contribution comes off before income tax. Through salary sacrifice, which also saves National Insurance, the cost falls to £1,800. Your employer adds at least 3% on top under auto-enrolment. The Salary Sacrifice Calculator shows other percentages.
Many auto-enrolment schemes work out the minimum on qualifying earnings, the slice of pay between £6,240 and £50,270, not on your full salary. On that basis the 5% minimum on £50,000 is £2,188.00 a year and your employer's 3% is £1,312.80. Your pension statement or scheme booklet says which basis applies.
What a pay rise is worth on £50,000
| Rise | Gross | Extra take-home a year | A month | You keep |
|---|---|---|---|---|
| 3.3% (NHS and council award) | £1,650 | £995 | £83 | 60% |
| 5% | £2,500 | £1,488 | £124 | 60% |
| £1,000 | £1,000 | £618 | £51 | 62% |
| £5,000 | £5,000 | £2,938 | £245 | 59% |
For a rise that includes a pension, student loan or back pay, use the Pay Rise Calculator.
One £50,000 salary or two of £25,000
A single earner on £50,000 takes home £39,519.60. Two earners on £25,000 each take home £43,039.20 between them, £3,519.60 a year more, because the second earner brings a second personal allowance and a second National Insurance threshold.
The single earner has one advantage: higher pension tax relief is within reach. A rise or bonus over £50,270 can be paid into a pension with 40% relief, while the two-earner couple only ever gets 20%.
£50,000 after tax in Scotland
| England, Wales and NI | Scotland | |
|---|---|---|
| Income tax | £7,486.00 | £8,982.05 |
| National Insurance | £2,994.40 | £2,994.40 |
| Take-home a year | £39,519.60 | £38,023.55 |
| Take-home a month | £3,293 | £3,169 |
You pay Scottish income tax if your main home is in Scotland, and your tax code starts with S. On £50,000 a Scottish taxpayer keeps £1,496.05 less a year. National Insurance is the same across the UK.
How £50,000 compares
Median pay for full-time employees was £39,039 in April 2025, according to the ONS Annual Survey of Hours and Earnings, so £50,000 is £10,961 (28.1%) above that figure.
| Salary | Take-home a year | A month | Difference |
|---|---|---|---|
| £45,000 | £35,920 | £2,993 | −£3,600 a year |
| £50,000 | £39,520 | £3,293 | This page |
| £55,000 | £42,457 | £3,538 | +£2,938 a year |
What these figures assume
- A 1257L tax code and a single job paid through PAYE
- England, Wales or Northern Ireland unless the Scotland table says otherwise
- No pension, student loan or taxable benefits unless shown
- HMRC 2026/27 rates; the personal allowance and higher rate threshold are frozen until April 2031
For a different tax code, pension type or bonus, use the Take-Home Pay Calculator.
Questions about £50,000
Is £50,000 a higher rate taxpayer?
No. The 40% higher rate starts at £50,270 in England, Wales and Northern Ireland, so £50,000 is taxed entirely at the basic rate above the personal allowance. In Scotland the 42% higher rate starts at £43,662, so a Scottish taxpayer on £50,000 does pay higher rate tax on part of their income.
Can I claim Marriage Allowance on £50,000?
Yes, if your spouse or civil partner earns less than £12,570 and you pay tax at the basic rate. They transfer £1,260 of their personal allowance to you, cutting your tax by up to £252 a year. In Scotland you must pay tax at the starter, basic or intermediate rate, so a Scottish taxpayer on £50,000 cannot claim.
How much is £50,000 a year per hour?
£50,000 a year is £25.64 an hour on a 37.5-hour week, £27.47 on a 35-hour week and £24.04 on a 40-hour week. After tax and National Insurance, the 37.5-hour figure is £20.27 an hour.
How much is £50,000 a month after tax with a pension?
With a 5% pension contribution on full salary, £50,000 leaves £3,126.63 a month, against £3,293.30 with no pension. With a Plan 2 student loan as well it is £2,972.02.
How much of a £5,000 bonus do I keep on £50,000?
You keep £2,937.80 of a £5,000 bonus on £50,000. The first £270 is taxed at 20% with 8% National Insurance, and the remaining £4,730 at 40% with 2%.