
£70,000 After Tax
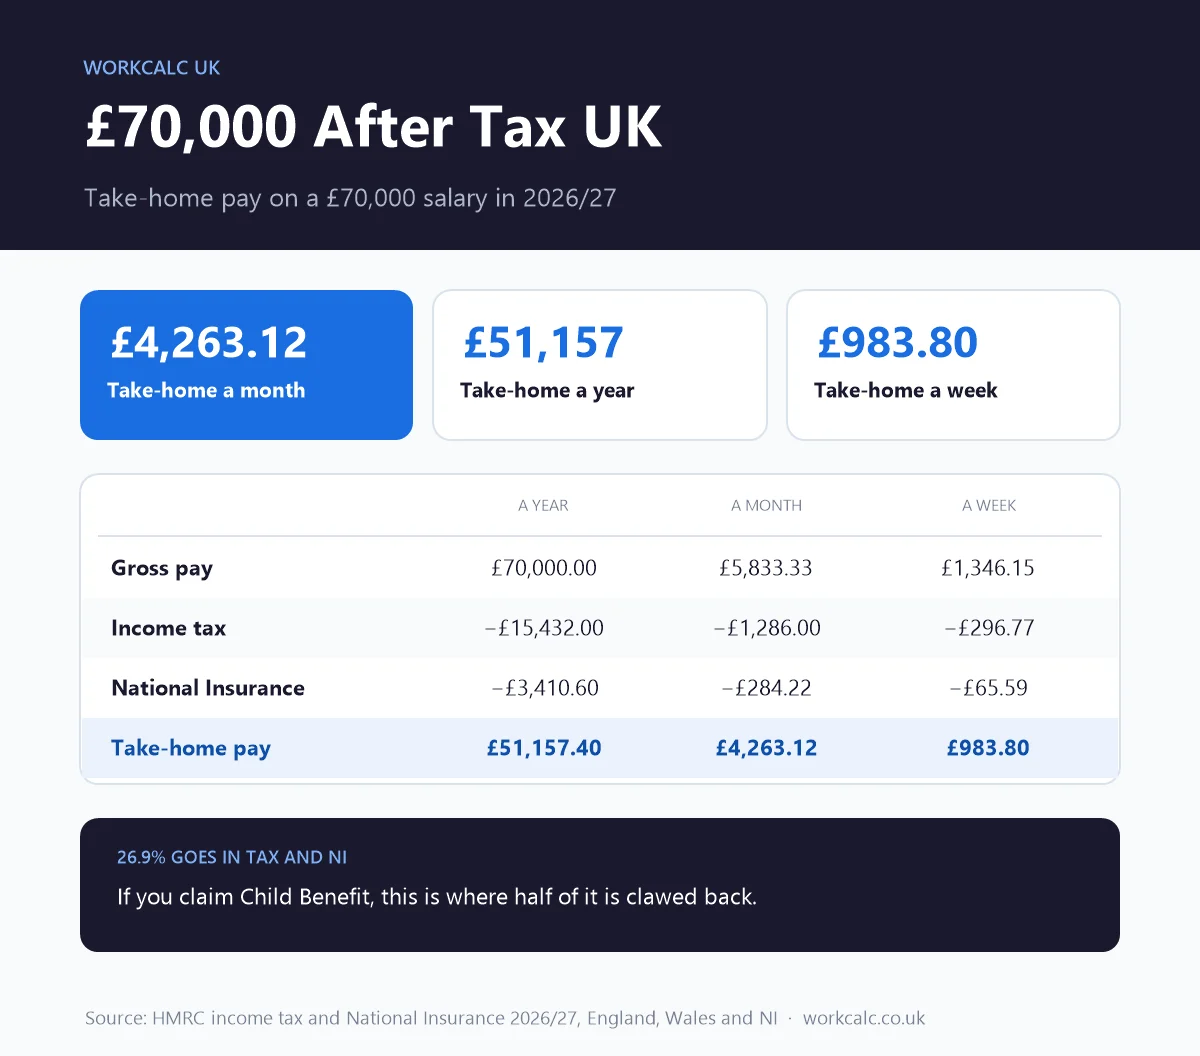
A £70,000 salary leaves £51,157 a year after income tax and National Insurance, which is £4,263 a month or £984 a week in 2026/27. If you claim Child Benefit, this is where half of it is clawed back.
Adjust for your situation
£70,000 after tax: the short answer
A salary of £70,000 leaves £51,157.40 after income tax and National Insurance in 2026/27. Paid monthly that is £4,263.12, and 26.9% of the salary goes on the two deductions.
| Year | Month | Week | |
|---|---|---|---|
| Gross pay | £70,000.00 | £5,833.33 | £1,346.15 |
| Income tax | −£15,432.00 | −£1,286.00 | −£296.77 |
| National Insurance | −£3,410.60 | −£284.22 | −£65.59 |
| Take-home pay | £51,157.40 | £4,263.12 | £983.80 |
How the tax on £70,000 is worked out
- Personal allowance: the first £12,570 is tax-free
- Basic rate: 20% on £37,700 = £7,540.00
- Higher rate: 40% on £19,730 = £7,892.00
- National Insurance: 8% on £37,700 = £3,016.00
- National Insurance above £50,270: 2% on £19,730 = £394.60
Your effective rate is 26.9%, but the rate on the next pound you earn is 42%. That second figure is the one to use when you weigh up overtime, a bonus or a pay rise.
£70,000: half your Child Benefit goes back
At £70,000 of adjusted net income the High Income Child Benefit Charge equals 50% of the Child Benefit you receive, because you are £10,000 over the £60,000 threshold and the charge is 1% for every £200. Each further £200 adds another 1% until it reaches 100% at £80,000.
Salary sacrifice is unusually effective here. Sacrificing £10,000 into a pension brings adjusted net income back to £60,000, removes the charge completely and costs only £5,800 of take-home pay, before counting the Child Benefit you keep.
The Scottish gap at £70,000
A Scottish taxpayer on £70,000 pays £1,950.05 more income tax than someone in the rest of the UK, taking home £49,207. Most of the difference comes from Scotland's 42% rate starting at £43,662 rather than £50,270.
Tax-free savings interest
As a higher rate taxpayer your Personal Savings Allowance is £500 a year, half the £1,000 available to basic rate taxpayers.
£70,000 a year as an hourly rate
| Contracted week | Before tax, per hour | After tax, per hour |
|---|---|---|
| 35 hours | £38.46 | £28.11 |
| 37.5 hours | £35.90 | £26.23 |
| 40 hours | £33.65 | £24.59 |
£70,000 is £35.90 an hour on a 37.5-hour week, and £26.23 of that reaches your bank account. Over 260 working days a year, £70,000 is £269.23 a day before tax and £196.76 after.
The Child Benefit charge on £70,000 in pounds
Child Benefit in 2026/27 is £27.05 a week for the eldest child and £17.90 for each other child. On £70,000 the charge is 50% of whatever your household receives:
| Children | Child Benefit a year | Charge on £70,000 | Benefit you keep |
|---|---|---|---|
| 1 child | £1,406.60 | £703.30 | £703.30 |
| 2 children | £2,337.40 | £1,168.70 | £1,168.70 |
| 3 children | £3,268.20 | £1,634.10 | £1,634.10 |
The charge is collected from the higher earner, even if their partner is the one who claims. Counting it, a parent of two on £70,000 is left with £49,988.70 from their salary, not £51,157.40. Each £1,000 paid into a pension by salary sacrifice cuts the charge by 5% of your Child Benefit, on top of the tax and National Insurance it saves.
£70,000 after tax with a student loan
| Plan | Repays above | A year | Take-home |
|---|---|---|---|
| Plan 1 | £26,900 | £3,879.00 | £47,278 |
| Plan 2 | £29,385 | £3,655.35 | £47,502 |
| Plan 4 (Scotland) | £33,795 | £3,258.45 | £47,899 |
| Plan 5 | £25,000 | £4,050.00 | £47,107 |
| Postgraduate Loan | £21,000 | £2,940.00 | £48,217 |
Every plan is in repayment at this salary. Each takes 9% of income above its own threshold, or 6% for a Postgraduate Loan, so two loans stack rather than replace each other.
Pension contributions on £70,000
A 5% contribution puts £3,500 a year into your pension. Through a net pay scheme it reduces take-home pay by £2,100, because the contribution comes off before income tax. Through salary sacrifice, which also saves National Insurance, the cost falls to £2,030. Your employer adds at least 3% on top under auto-enrolment. The Salary Sacrifice Calculator shows other percentages.
If your scheme uses qualifying earnings, contributions are only due on pay between £6,240 and £50,270. That caps the 5% minimum at £2,201.50 a year and the employer's 3% at £1,320.90, however far above £50,270 you earn. Many employers of people on £70,000 pay on full salary instead, so check your scheme booklet.
What a pay rise is worth on £70,000
| Rise | Gross | Extra take-home a year | A month | You keep |
|---|---|---|---|---|
| 3.3% (NHS and council award) | £2,310 | £1,340 | £112 | 58% |
| 5% | £3,500 | £2,030 | £169 | 58% |
| £1,000 | £1,000 | £580 | £48 | 58% |
| £5,000 | £5,000 | £2,900 | £242 | 58% |
For a rise that includes a pension, student loan or back pay, use the Pay Rise Calculator.
One £70,000 salary or two of £35,000
The Child Benefit charge looks at one person's income, not the household's. That produces an odd result. A couple earning £35,000 each has the same £70,000 coming in, pays no charge at all, and takes home £57,439.20 between them. A single earner on £70,000 takes home £51,157.40 and loses half their Child Benefit.
Before the charge, the two-earner couple is £6,281.80 a year better off. With two children the gap grows to £7,450.50. Two earners on £59,000 each, £118,000 in total, would still keep every pound of Child Benefit.
£70,000 after tax in Scotland
| England, Wales and NI | Scotland | |
|---|---|---|
| Income tax | £15,432.00 | £17,382.05 |
| National Insurance | £3,410.60 | £3,410.60 |
| Take-home a year | £51,157.40 | £49,207.35 |
| Take-home a month | £4,263 | £4,101 |
You pay Scottish income tax if your main home is in Scotland, and your tax code starts with S. On £70,000 a Scottish taxpayer keeps £1,950.05 less a year. National Insurance is the same across the UK.
How £70,000 compares
Median pay for full-time employees was £39,039 in April 2025, according to the ONS Annual Survey of Hours and Earnings, so £70,000 is £30,961 (79.3%) above that figure.
| Salary | Take-home a year | A month | Difference |
|---|---|---|---|
| £65,000 | £48,257 | £4,021 | −£2,900 a year |
| £70,000 | £51,157 | £4,263 | This page |
| £75,000 | £54,057 | £4,505 | +£2,900 a year |
What these figures assume
- A 1257L tax code and a single job paid through PAYE
- England, Wales or Northern Ireland unless the Scotland table says otherwise
- No pension, student loan or taxable benefits unless shown
- HMRC 2026/27 rates; the personal allowance and higher rate threshold are frozen until April 2031
For a different tax code, pension type or bonus, use the Take-Home Pay Calculator.
Questions about £70,000
How much Child Benefit do I lose on £70,000?
Half of it. The charge is 1% of your Child Benefit for every £200 of adjusted net income above £60,000, and £70,000 is £10,000 over, so the charge equals 50%. Pension contributions that reduce adjusted net income reduce the charge as well.
How much more tax do Scottish taxpayers pay on £70,000?
£1,950.05 a year. Income tax on £70,000 is £17,382.05 in Scotland against £15,432.00 in England, Wales and Northern Ireland, leaving a Scottish taxpayer £49,207 after tax and National Insurance.
How much is £70,000 a year per hour?
£70,000 a year is £35.90 an hour on a 37.5-hour week, £38.46 on a 35-hour week and £33.65 on a 40-hour week. After tax and National Insurance, the 37.5-hour figure is £26.23 an hour.
Is the Child Benefit charge based on household income?
No. It is based on the adjusted net income of the higher earner only. A single earner on £70,000 loses half their Child Benefit, while a couple earning £35,000 each, with the same total income, loses none.
How much is £70,000 a month after tax with a pension?
With a 5% pension contribution on full salary, £70,000 leaves £4,088.12 a month, against £4,263.12 with no pension. The contribution also lowers the income used for the Child Benefit charge to £66,500.