
Self-Employed Tax Calculator
Enter your self-employed income and expenses to see your income tax, Class 4 National Insurance and take-home pay for 2026/27, how much to set aside each month, and exactly when HMRC wants paying.
Your business, 2026/27
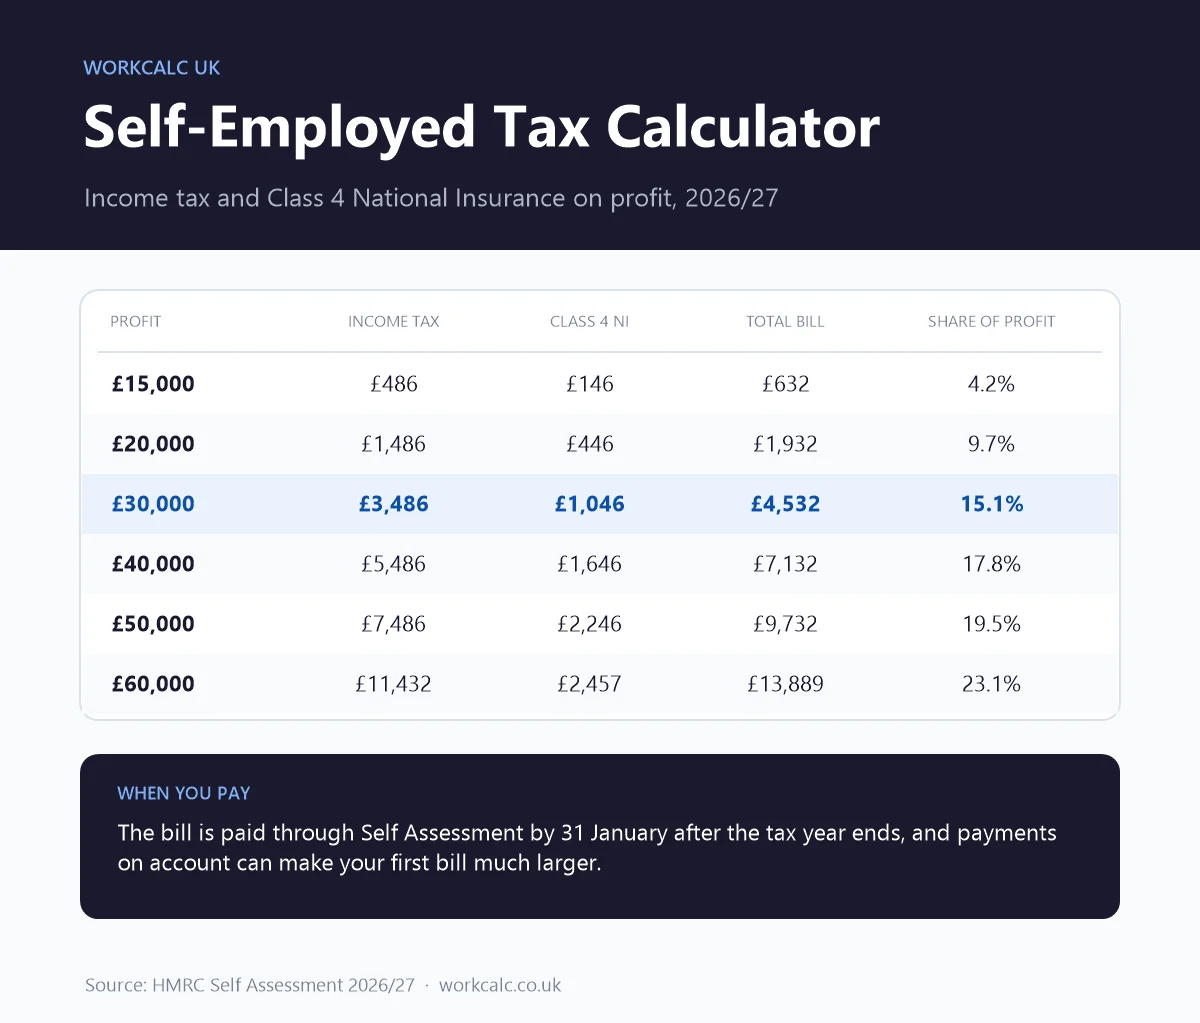
Self-employed tax by profit, 2026/27
England, Wales and Northern Ireland, no other income, pension or student loan.
| Profit | Income tax | Class 4 NI | Total bill | Share of profit | Take-home a month |
|---|---|---|---|---|---|
| £15,000 | £486 | £146 | £632 | 4.2% | £1,197 |
| £20,000 | £1,486 | £446 | £1,932 | 9.7% | £1,506 |
| £30,000 | £3,486 | £1,046 | £4,532 | 15.1% | £2,122 |
| £40,000 | £5,486 | £1,646 | £7,132 | 17.8% | £2,739 |
| £50,000 | £7,486 | £2,246 | £9,732 | 19.5% | £3,356 |
| £60,000 | £11,432 | £2,457 | £13,889 | 23.1% | £3,843 |
| £80,000 | £19,432 | £2,857 | £22,289 | 27.9% | £4,809 |
| £100,000 | £27,432 | £3,257 | £30,689 | 30.7% | £5,776 |
Self-employed people pay income tax on profit above £12,570 at 20%, 40% and 45%, plus Class 4 National Insurance at 6% on profit between £12,570 and £50,270 and 2% above. On £30,000 of profit in 2026/27 the bill is £4,531.80, about 15% of profit. It is paid through Self Assessment by 31 January after the tax year ends, and payments on account can make your first bill much larger.
How self-employed tax is worked out
Income tax is then charged on your profit plus any other income, after your £12,570 Personal Allowance, using the same bands as employees. Class 4 National Insurance is charged on the profit alone:
- 6% on profits between £12,570 and £50,270
- 2% on profits above £50,270
Employees pay 8% National Insurance on the same band, so a sole trader on £40,000 pays £548.60 less NI than an employee on the same pay. The trade-off is no employer pension, sick pay or holiday pay.
£45,000 income, £5,000 expenses, 2026/27
Class 2 National Insurance
Compulsory Class 2 National Insurance ended in April 2024. If your profits are £7,105 or more in 2026/27, you are treated as having paid it and get a qualifying year towards your State Pension automatically. Below that, you can pay voluntary Class 2 at £3.65 a week, £189.80 for the year, to protect your record.
Expenses and the £1,000 trading allowance
You can deduct costs incurred wholly and exclusively for the business: stock and materials, equipment, software, phone and internet business use, travel, insurance, professional fees and accountancy. Simplified expenses let you claim flat rates instead of working out actual costs:
- Vehicle mileage: 45p a mile for the first 10,000 business miles, then 25p
- Working from home: £10 to £26 a month depending on hours worked at home
If your costs are small, you can claim the £1,000 trading allowance instead of expenses. If your total self-employed income is £1,000 or less, you usually do not need to tell HMRC at all.
Payments on account and your first tax bill
Self-employed tax is paid in arrears through Self Assessment. For 2026/27 you must file your return and pay by 31 January 2028. If your bill is £1,000 or more, and less than 80% of your tax was collected at source through PAYE, HMRC also asks for two payments on account towards the next year, each half of this year's bill.
That is why the first bill is a shock. It contains the whole of your first year's tax plus half of next year's in advance:
First year, £40,000 profit in 2026/27
From the second year, you are paying roughly one year's tax each year, split between January and July, with a balancing payment if your profit rises. If you expect your profit to fall, you can apply to reduce your payments on account. Student loan repayments are not included in payments on account.
How much to set aside
At a steady profit, putting aside your total bill divided by 12 each month covers the tax. In your first year, save more: the calculator shows the amount needed to cover everything due by 31 January 2028 when you tick the first-year box. As a rule of thumb, 20% of profit covers most basic rate sole traders and 30% covers most higher rate ones, but the exact figure depends on your profit.
Related tool Day Rate Calculator: convert a contract rate into a salary equivalent →Side income alongside a job
If you have a job, your salary normally uses your Personal Allowance through PAYE, so every pound of side profit is taxed at your marginal rate. Class 4 National Insurance, though, is worked out on your self-employed profit on its own.
With a £30,000 salary and £10,000 of side profit, you pay £2,000 of income tax through Self Assessment and no Class 4, because the profit is below £12,570. At £15,000 of side profit, the bill is £3,000 of income tax plus £145.80 of Class 4. Enter your salary in the calculator to see your own figure.
Making Tax Digital for Income Tax
From 6 April 2026, sole traders and landlords with qualifying income over £50,000 must keep digital records and send quarterly updates to HMRC using compatible software, then file a final return. The threshold falls to £30,000 from April 2027 and £20,000 from April 2028. Qualifying income is your gross self-employment and property income before expenses, taken from an earlier tax return. Quarterly updates are summaries of income and expenses; they do not change when you pay.
Key dates for 2026/27
| Date | What happens |
|---|---|
| 6 April 2026 | Tax year starts; Making Tax Digital begins for income over £50,000 |
| 5 April 2027 | Tax year ends |
| 5 October 2027 | Deadline to register for Self Assessment if you started in 2026/27 |
| 31 January 2028 | File online and pay the 2026/27 bill, plus any first payment on account |
| 31 July 2028 | Second payment on account for 2027/28 |
Late filing brings an automatic £100 penalty, and late payment brings interest and further penalties, so it is worth filing well before January.
Reducing your tax legally
- Claim every allowable expense, including simplified mileage and use of home.
- Pay into a personal pension. Your provider adds 20%, and higher rate relief is claimed on your return. Compare contribution methods with the Pension Contribution Calculator.
- Watch the £100,000 line, where you lose £1 of Personal Allowance for every £2. Pension contributions reduce the income used for this.
- Consider timing of large purchases of equipment, which can often be deducted in full in the year you buy them.
What this calculator does not cover
- Limited companies, which pay Corporation Tax and take salary and dividends instead.
- Partnerships, losses, capital allowances detail and VAT.
- Other income such as rent, savings interest and dividends.
- Payments on account already made for 2026/27 if this is not your first year.
Sources
- GOV.UK, Self-employed National Insurance rates, 2026 to 2027
- GOV.UK, Understand your Self Assessment tax bill: payments on account
- HMRC, Making Tax Digital for Income Tax
- HMRC income tax rates and thresholds for 2026/27
Frequently asked questions
Self-employed tax, National Insurance and Self Assessment.
How much tax do I pay when self-employed?
You pay income tax on your profit after the £12,570 Personal Allowance, at 20%, 40% and 45%, plus Class 4 National Insurance at 6% on profits between £12,570 and £50,270 and 2% above. On £30,000 of profit in 2026/27 that is £3,486 income tax and £1,045.80 National Insurance, £4,531.80 in total.
How much should I put aside for tax when self-employed?
It depends on your profit. In 2026/27 the bill is about 15% of profit at £30,000, 19.5% at £50,000 and 23% at £60,000. Many sole traders set aside 25% to 30% to be safe, especially in their first year when payments on account can make the first bill 150% of the year's tax.
Do self-employed people still pay Class 2 National Insurance?
Not compulsorily. Class 2 was abolished from April 2024. If your profits are £7,105 or more in 2026/27 you get a National Insurance credit automatically. Below that, you can pay voluntary Class 2 at £3.65 a week to protect your State Pension record.
What is a payment on account?
An advance payment towards next year's tax bill. If your Self Assessment bill is £1,000 or more, and less than 80% of your tax was collected at source, HMRC asks for two payments on account, each half of last year's bill, due on 31 January and 31 July.
Why is my first self-employed tax bill so big?
Because the first bill includes the whole of the first year's tax plus the first payment on account for the next year. On £40,000 of profit in 2026/27, £10,697.70 is due on 31 January 2028 and another £3,565.90 on 31 July 2028.
Do I pay tax on side income if I also have a job?
Yes. Your job normally uses your Personal Allowance, so side profit is taxed at your marginal rate from the first pound. Class 4 National Insurance is worked out on the profit alone, so £10,000 of side profit alongside a £30,000 job means £2,000 income tax and no Class 4.
Do I need to register as self-employed?
You need to register for Self Assessment if your self-employed income is over £1,000 in a tax year, by 5 October after the end of that tax year. Below £1,000 the trading allowance means you usually do not need to tell HMRC.
Does Making Tax Digital apply to me?
From 6 April 2026, sole traders and landlords with qualifying income over £50,000 must keep digital records and send quarterly updates using compatible software. The threshold falls to £30,000 from April 2027 and £20,000 from April 2028. Qualifying income is your gross self-employment and property income, before expenses.