
£110,000 After Tax
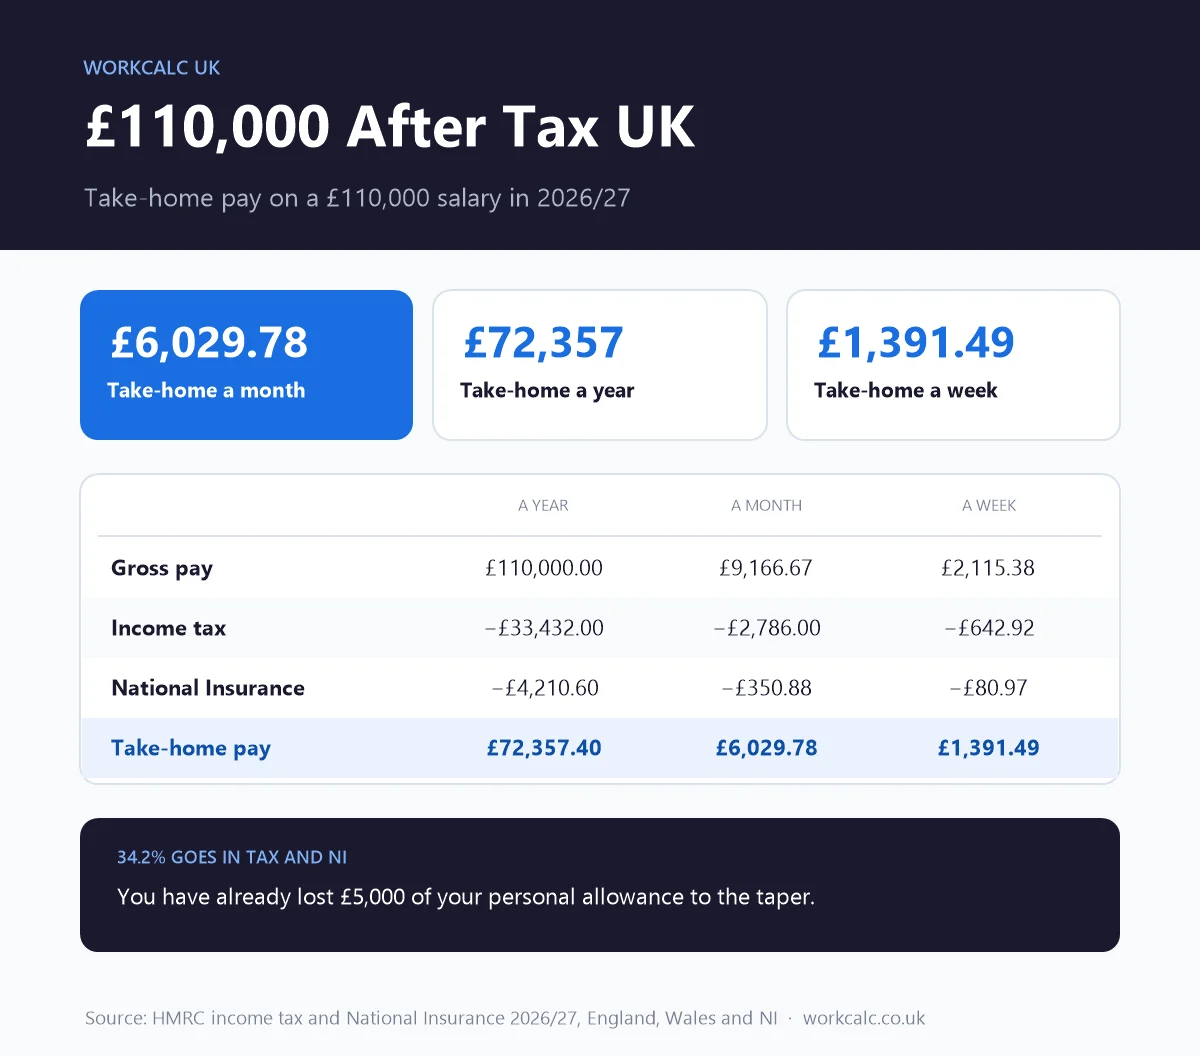
A £110,000 salary leaves £72,357 a year after income tax and National Insurance, which is £6,030 a month or £1,391 a week in 2026/27. You have already lost £5,000 of your personal allowance to the taper.
Adjust for your situation
£110,000 after tax: the short answer
A salary of £110,000 leaves £72,357.40 after income tax and National Insurance in 2026/27. Paid monthly that is £6,029.78, and 34.2% of the salary goes on the two deductions.
| Year | Month | Week | |
|---|---|---|---|
| Gross pay | £110,000.00 | £9,166.67 | £2,115.38 |
| Income tax | −£33,432.00 | −£2,786.00 | −£642.92 |
| National Insurance | −£4,210.60 | −£350.88 | −£80.97 |
| Take-home pay | £72,357.40 | £6,029.78 | £1,391.49 |
How the tax on £110,000 is worked out
- Personal allowance: reduced from £12,570 to £7,570 by the £100,000 taper
- Basic rate: 20% on £37,700 = £7,540.00
- Higher rate: 40% on £64,730 = £25,892.00
- National Insurance: 8% on £37,700 = £3,016.00
- National Insurance above £50,270: 2% on £59,730 = £1,194.60
Your effective rate is 34.2%, but the rate on the next pound you earn is 62%. That second figure is the one to use when you weigh up overtime, a bonus or a pay rise.
£110,000: how much personal allowance you keep
On £110,000 you are £10,000 into the personal allowance taper, so £5,000 of your allowance has gone. Your tax-free amount falls from £12,570 to £7,570, and HMRC will usually adjust your tax code to 757L to reflect it, which you can check with the tax code calculator. The lost allowance adds £2,000 to your income tax bill.
Income from here to £125,140 is taxed at an effective 62% including National Insurance, so a £1,000 rise adds just £380.00 to take-home pay.
Sacrificing £10,000 into a pension
Salary sacrifice brings adjusted net income back to £100,000 and restores the full allowance. Sacrificing £10,000 reduces take-home pay by only £3,800, so £10,000 reaches your pension at a net cost of 38% of the amount invested.
Childcare and the £100,000 line
Parents with adjusted net income above £100,000 lose Tax-Free Childcare and the extra funded childcare hours. The same £10,000 sacrifice that restores the allowance can restore that support too.
£110,000 a year as an hourly rate
| Contracted week | Before tax, per hour | After tax, per hour |
|---|---|---|
| 35 hours | £60.44 | £39.76 |
| 37.5 hours | £56.41 | £37.11 |
| 40 hours | £52.88 | £34.79 |
£110,000 is £56.41 an hour on a 37.5-hour week, but each extra hour worked is worth only £21.44 after the 62% rate. Over 260 working days a year, £110,000 is £423.08 a day before tax and £278.30 after.
Personal allowance from £100,000 to £125,140
The allowance shrinks by £1 for every £2 of income over £100,000. This is where £110,000 sits on that slope:
| Salary | Personal allowance | Extra tax from the lost allowance | Take-home a year |
|---|---|---|---|
| £100,000 | £12,570 | £0.00 | £68,557.40 |
| £105,000 | £10,070 | £1,000.00 | £70,457.40 |
| £110,000 | £7,570 | £2,000.00 | £72,357.40 |
| £115,000 | £5,070 | £3,000.00 | £74,257.40 |
| £120,000 | £2,570 | £4,000.00 | £76,157.40 |
| £125,140 | £0 | £5,028.00 | £78,110.60 |
Between the first and last rows, salary rises by £25,140 and take-home pay by £9,553.20. On £110,000 you are 40% of the way down the slope, with £15,140 of income still to pass through the 62% rate if your pay keeps rising.
£110,000 after tax with a student loan
| Plan | Repays above | A year | Take-home |
|---|---|---|---|
| Plan 1 | £26,900 | £7,479.00 | £64,878 |
| Plan 2 | £29,385 | £7,255.35 | £65,102 |
| Plan 4 (Scotland) | £33,795 | £6,858.45 | £65,499 |
| Plan 5 | £25,000 | £7,650.00 | £64,707 |
| Postgraduate Loan | £21,000 | £5,340.00 | £67,017 |
Every plan is in repayment at this salary. Each takes 9% of income above its own threshold, or 6% for a Postgraduate Loan, so two loans stack rather than replace each other.
Pension contributions on £110,000
A 5% contribution puts £5,500 a year into your pension. Through a net pay scheme it reduces take-home pay by £2,200, because the contribution comes off before income tax. Through salary sacrifice, which also saves National Insurance, the cost falls to £2,090. Your employer adds at least 3% on top under auto-enrolment. The Salary Sacrifice Calculator shows other percentages.
If your scheme uses qualifying earnings, contributions are only due on pay between £6,240 and £50,270. That caps the 5% minimum at £2,201.50 a year and the employer's 3% at £1,320.90, however far above £50,270 you earn. Many employers of people on £110,000 pay on full salary instead, so check your scheme booklet.
What a pay rise is worth on £110,000
| Rise | Gross | Extra take-home a year | A month | You keep |
|---|---|---|---|---|
| 3.3% (NHS and council award) | £3,630 | £1,379 | £115 | 38% |
| 5% | £5,500 | £2,090 | £174 | 38% |
| £1,000 | £1,000 | £380 | £32 | 38% |
| £5,000 | £5,000 | £1,900 | £158 | 38% |
For a rise that includes a pension, student loan or back pay, use the Pay Rise Calculator.
£110,000 on a four-day week
Four days on a £110,000 full-time salary is £88,000 pro rata, which leaves £61,597.40 a year or £5,133.12 a month. You give up 20% of your hours and keep 85% of your take-home pay, the best ratio of any salary on this site, because the first £10,000 you give up was only worth £3,800 to you.
The cut also restores the full personal allowance and brings adjusted net income back under £100,000, which is the test for Tax-Free Childcare and the funded childcare hours for working parents. For a family using both, a fifth working day at this salary can cost more in lost support than it earns.
£110,000 after tax in Scotland
| England, Wales and NI | Scotland | |
|---|---|---|
| Income tax | £33,432.00 | £37,482.05 |
| National Insurance | £4,210.60 | £4,210.60 |
| Take-home a year | £72,357.40 | £68,307.35 |
| Take-home a month | £6,030 | £5,692 |
You pay Scottish income tax if your main home is in Scotland, and your tax code starts with S. On £110,000 a Scottish taxpayer keeps £4,050.05 less a year. National Insurance is the same across the UK.
How £110,000 compares
Median pay for full-time employees was £39,039 in April 2025, according to the ONS Annual Survey of Hours and Earnings, so £110,000 is £70,961 (181.8%) above that figure.
| Salary | Take-home a year | A month | Difference |
|---|---|---|---|
| £105,000 | £70,457 | £5,871 | −£1,900 a year |
| £110,000 | £72,357 | £6,030 | This page |
| £115,000 | £74,257 | £6,188 | +£1,900 a year |
What these figures assume
- A 1257L tax code and a single job paid through PAYE
- England, Wales or Northern Ireland unless the Scotland table says otherwise
- No pension, student loan or taxable benefits unless shown
- HMRC 2026/27 rates; the personal allowance and higher rate threshold are frozen until April 2031
For a different tax code, pension type or bonus, use the Take-Home Pay Calculator.
Questions about £110,000
What is my personal allowance on £110,000?
£7,570. The standard £12,570 allowance is reduced by £1 for every £2 of adjusted net income above £100,000, and £110,000 is £10,000 over, so £5,000 is withdrawn. Pension contributions that reduce adjusted net income restore it.
How can I avoid the 62% tax rate on £110,000?
Bring adjusted net income down to £100,000, usually through salary sacrifice or extra pension contributions. Sacrificing £10,000 on £110,000 cuts take-home pay by only £3,800, because the whole amount would otherwise be taxed at 62%.
How much is £110,000 a year per hour?
£110,000 a year is £56.41 an hour on a 37.5-hour week, £60.44 on a 35-hour week and £52.88 on a 40-hour week. After tax and National Insurance, the 37.5-hour figure is £37.11 an hour.
How much tax do I pay on £110,000?
On £110,000 you pay £33,432.00 income tax and £4,210.60 National Insurance in 2026/27, which is 34.2% of the salary. £2,000 of that tax comes from losing £5,000 of personal allowance.
How much is £110,000 a month after tax with a 10% pension?
With a 10% pension contribution, £110,000 leaves £5,646.45 a month, against £6,029.78 with no pension. The £11,000 contribution restores the full personal allowance, so it costs only £4,600.00 of take-home pay.