
£100,000 After Tax
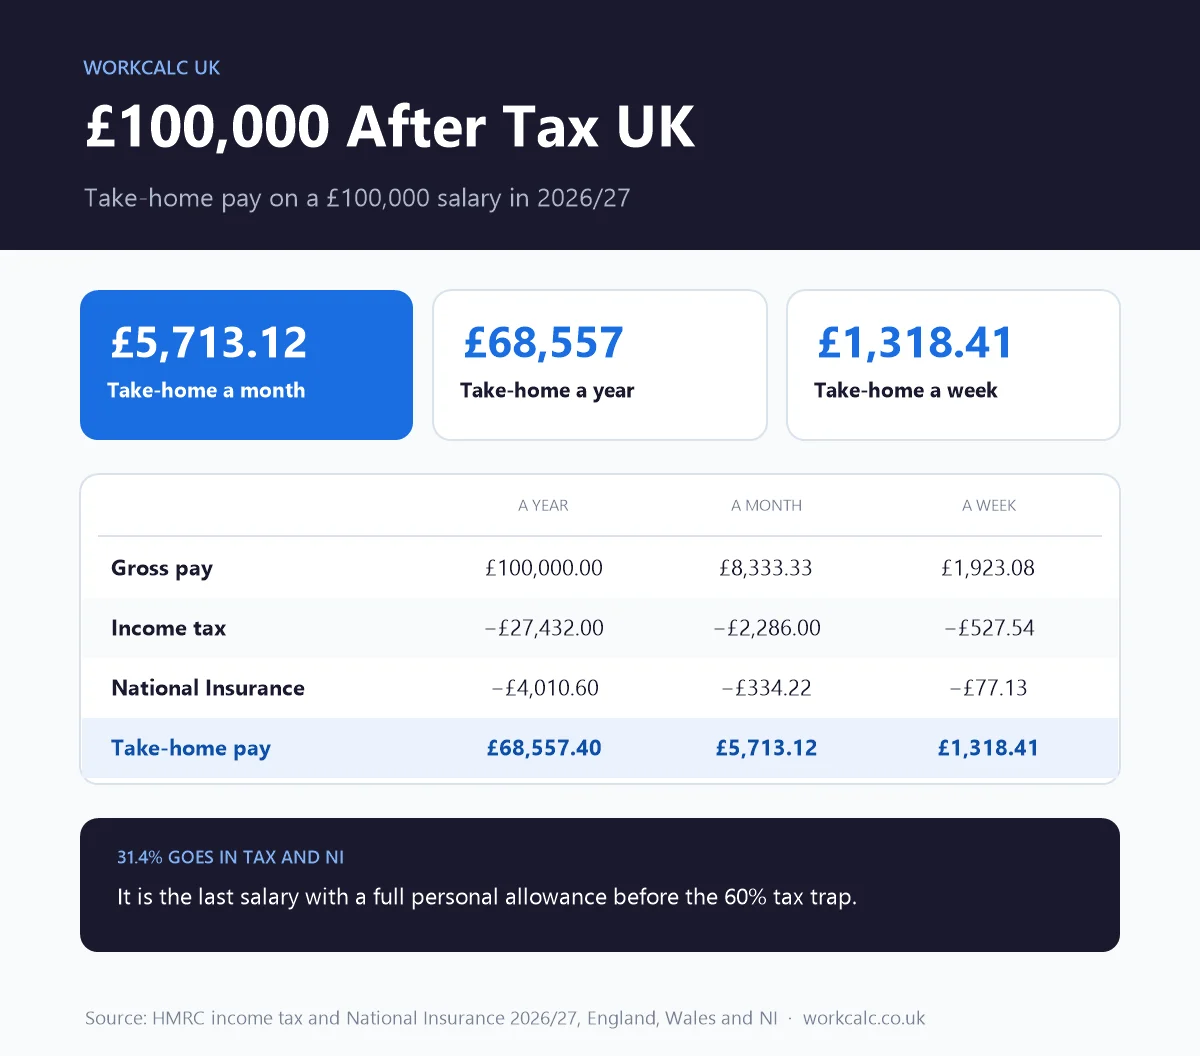
A £100,000 salary leaves £68,557 a year after income tax and National Insurance, which is £5,713 a month or £1,318 a week in 2026/27. It is the last salary with a full personal allowance before the 60% tax trap.
Adjust for your situation
£100,000 after tax: the short answer
A salary of £100,000 leaves £68,557.40 after income tax and National Insurance in 2026/27. Paid monthly that is £5,713.12, and 31.4% of the salary goes on the two deductions.
| Year | Month | Week | |
|---|---|---|---|
| Gross pay | £100,000.00 | £8,333.33 | £1,923.08 |
| Income tax | −£27,432.00 | −£2,286.00 | −£527.54 |
| National Insurance | −£4,010.60 | −£334.22 | −£77.13 |
| Take-home pay | £68,557.40 | £5,713.12 | £1,318.41 |
How the tax on £100,000 is worked out
- Personal allowance: the first £12,570 is tax-free
- Basic rate: 20% on £37,700 = £7,540.00
- Higher rate: 40% on £49,730 = £19,892.00
- National Insurance: 8% on £37,700 = £3,016.00
- National Insurance above £50,270: 2% on £49,730 = £994.60
Your effective rate is 31.4%, but the rate on the next pound you earn is 62%. That second figure is the one to use when you weigh up overtime, a bonus or a pay rise.
£100,000: where the 60% tax trap begins
£100,000 is the last salary with the full £12,570 personal allowance. Above it you lose £1 of allowance for every £2 of adjusted net income, until the allowance has gone completely at £125,140. The lost allowance is then taxed at 40%, so income in that range is effectively taxed at 60%, plus 2% National Insurance.
The effect on a rise is stark. A £1,000 rise from £100,000 adds only £380.00 to take-home pay, and a £5,000 rise adds £1,900. A Plan 2 student loan would take another 9p of each extra pound.
Childcare support is at stake too
Tax-Free Childcare and the extra funded childcare hours for working parents both stop if either parent's adjusted net income is expected to be over £100,000. On exactly £100,000 you still qualify, but a small rise or bonus could remove support worth thousands of pounds a year.
How to stay at £100,000
Salary sacrifice and personal pension contributions both reduce adjusted net income. If you receive a rise or bonus, paying the extra into your pension keeps you at £100,000, protects the allowance and puts the full amount into your pension instead of losing 62% of it.
£100,000 a year as an hourly rate
| Contracted week | Before tax, per hour | After tax, per hour |
|---|---|---|
| 35 hours | £54.95 | £37.67 |
| 37.5 hours | £51.28 | £35.16 |
| 40 hours | £48.08 | £32.96 |
£100,000 is £51.28 an hour on a 37.5-hour week. The next hour of paid overtime would be worth £19.49 after deductions, less than the £23.79 it is worth to someone on £80,000. Over 260 working days a year, £100,000 is £384.62 a day before tax and £263.68 after.
What a bonus is worth on £100,000
Every pound of bonus between £100,000 and £125,140 loses 40% in income tax, a further 20% through the shrinking personal allowance, and 2% in National Insurance:
| Bonus | Extra take-home | Lost to tax and NI | Personal allowance left |
|---|---|---|---|
| £1,000 | £380.00 | £620.00 | £12,070 |
| £5,000 | £1,900.00 | £3,100.00 | £10,070 |
| £10,000 | £3,800.00 | £6,200.00 | £7,570 |
| £25,140 | £9,553.20 | £15,586.80 | £0 |
A £25,140 bonus, enough to wipe out the whole allowance, adds £9,553.20 to take-home pay. Paid into a pension by bonus sacrifice, the full £25,140 is invested. That is the clearest case in the tax system for taking pension over cash, provided you have annual allowance to use.
£100,000 after tax with a student loan
| Plan | Repays above | A year | Take-home |
|---|---|---|---|
| Plan 1 | £26,900 | £6,579.00 | £61,978 |
| Plan 2 | £29,385 | £6,355.35 | £62,202 |
| Plan 4 (Scotland) | £33,795 | £5,958.45 | £62,599 |
| Plan 5 | £25,000 | £6,750.00 | £61,807 |
| Postgraduate Loan | £21,000 | £4,740.00 | £63,817 |
Every plan is in repayment at this salary. Each takes 9% of income above its own threshold, or 6% for a Postgraduate Loan, so two loans stack rather than replace each other.
Pension contributions on £100,000
A 5% contribution puts £5,000 a year into your pension. Through a net pay scheme it reduces take-home pay by £3,000, because the contribution comes off before income tax. Through salary sacrifice, which also saves National Insurance, the cost falls to £2,900. Your employer adds at least 3% on top under auto-enrolment. The Salary Sacrifice Calculator shows other percentages.
If your scheme uses qualifying earnings, contributions are only due on pay between £6,240 and £50,270. That caps the 5% minimum at £2,201.50 a year and the employer's 3% at £1,320.90, however far above £50,270 you earn. Many employers of people on £100,000 pay on full salary instead, so check your scheme booklet.
What a pay rise is worth on £100,000
| Rise | Gross | Extra take-home a year | A month | You keep |
|---|---|---|---|---|
| 3.3% (NHS and council award) | £3,300 | £1,254 | £105 | 38% |
| 5% | £5,000 | £1,900 | £158 | 38% |
| £1,000 | £1,000 | £380 | £32 | 38% |
| £5,000 | £5,000 | £1,900 | £158 | 38% |
For a rise that includes a pension, student loan or back pay, use the Pay Rise Calculator.
One £100,000 salary or two of £50,000
A single earner on £100,000 takes home £68,557.40. Two earners on £50,000 each take home £79,039.20 between them, £10,481.80 a year more. Neither of the two pays any 40% tax, while the single earner pays it on £49,730.
The couple is also much further from trouble. Each of them could get a £50,000 rise before reaching the personal allowance taper, and neither is near the £100,000 limit for Tax-Free Childcare. The single earner is one bonus away from both.
£100,000 after tax in Scotland
| England, Wales and NI | Scotland | |
|---|---|---|
| Income tax | £27,432.00 | £30,732.05 |
| National Insurance | £4,010.60 | £4,010.60 |
| Take-home a year | £68,557.40 | £65,257.35 |
| Take-home a month | £5,713 | £5,438 |
You pay Scottish income tax if your main home is in Scotland, and your tax code starts with S. On £100,000 a Scottish taxpayer keeps £3,300.05 less a year. National Insurance is the same across the UK.
How £100,000 compares
Median pay for full-time employees was £39,039 in April 2025, according to the ONS Annual Survey of Hours and Earnings, so £100,000 is £60,961 (156.2%) above that figure.
| Salary | Take-home a year | A month | Difference |
|---|---|---|---|
| £95,000 | £65,657 | £5,471 | −£2,900 a year |
| £100,000 | £68,557 | £5,713 | This page |
| £105,000 | £70,457 | £5,871 | +£1,900 a year |
What these figures assume
- A 1257L tax code and a single job paid through PAYE
- England, Wales or Northern Ireland unless the Scotland table says otherwise
- No pension, student loan or taxable benefits unless shown
- HMRC 2026/27 rates; the personal allowance and higher rate threshold are frozen until April 2031
For a different tax code, pension type or bonus, use the Take-Home Pay Calculator.
Questions about £100,000
What is the 60% tax trap at £100,000?
Between £100,000 and £125,140 your personal allowance is withdrawn at £1 for every £2 you earn. For each £2 you pay 40% on the pay itself and also lose £1 of allowance, which is then taxed at 40%. That makes an effective rate of 60%, or 62% with National Insurance, so a £1,000 rise leaves you £380.00.
Will I lose Tax-Free Childcare on £100,000?
Not on exactly £100,000. Eligibility ends when adjusted net income is expected to be over £100,000, so a rise or bonus could remove it. Pension contributions reduce adjusted net income and can keep you eligible.
How much is £100,000 a year per hour?
£100,000 a year is £51.28 an hour on a 37.5-hour week, £54.95 on a 35-hour week and £48.08 on a 40-hour week. After tax and National Insurance, the 37.5-hour figure is £35.16 an hour.
How much is £100,000 a month after tax with a pension?
With a 5% pension contribution on full salary, £100,000 leaves £5,463.12 a month, against £5,713.12 with no pension. The £5,000 contribution costs £3,000 of take-home pay.
What is adjusted net income?
It is your total taxable income before the personal allowance, less certain reliefs such as pension contributions and Gift Aid donations. HMRC uses it for the £100,000 personal allowance taper, the childcare limit and the Child Benefit charge.